It’s no secret that Tesla has achieved a remarkable evolution from a niche electric vehicle maker to a multi-faceted technology company.
Yet Tesla shares have experienced meaningful pressure this year, lagging the broader market amid concerns over slowing vehicle deliveries and margin compression.
Also Read :Bitcoin could hit $1 million by 2035 if store of value market grows, says Bitwise’s Matt Hougan
Still, as we approach the company’s upcoming earnings report, there’s reason to believe this recent underperformance is a temporary breather rather than the start of a deeper downturn. With several meaningful catalysts on the horizon — from accelerating energy storage growth and Full Self-Driving (FSD) monetization to tangible progress on Optimus and Robotaxi initiatives — Tesla appears well-positioned for a potential near-term rebound.
Also Read :SpaceX IPO countdown accelerates — Musk’s rocket juggernaut fast-tracks vesting
Digging Deeper into Earnings Projections
The early-year caution around Tesla is understandable. First-quarter vehicle deliveries came in at 358,023 units, missing consensus estimates of approximately 365,000 and marking the second consecutive quarter of softer-than-expected results. This has contributed to a subdued start for the stock in 2026, shedding nearly 14% year-to-date.
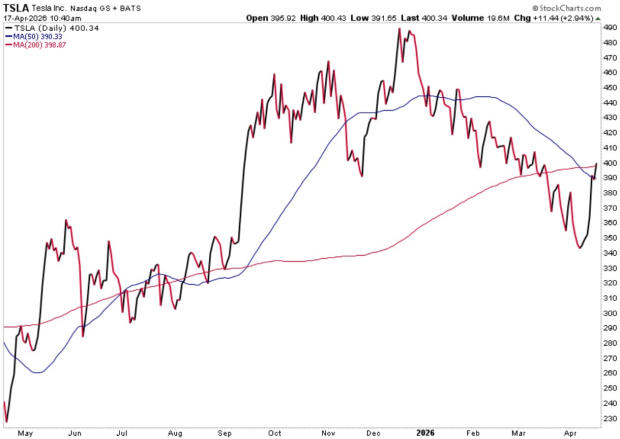
Image Source: StockCharts
But Tesla’s long-term story has always been about more than just quarterly vehicle sales, and the upcoming earnings call could serve as a timely reminder of that broader vision.
Also Read :Your daily horoscope: April 17, 2026 predictions
Looking at projected earnings, analysts currently expect Tesla to report first-quarter EPS of 36 cents (up roughly 33% year-over-year), with revenue around $22 billion (+13.4%). These figures still point to solid expansion, particularly when factoring in the rapidly growing energy storage business and software/services revenue streams.
In our view, the market has been overly focused on near-term automotive headline numbers while underappreciating the accelerating contributions from higher-margin segments.
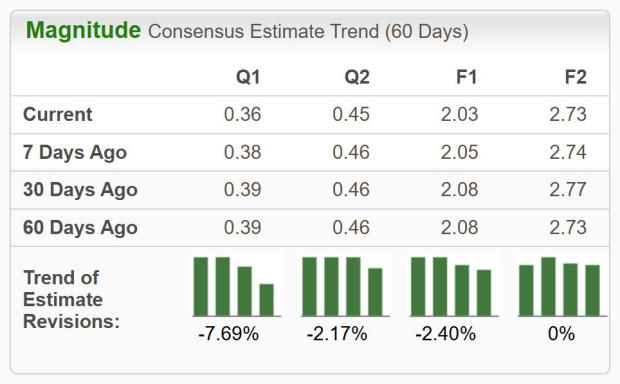
Image Source: Zacks Investment Research
Momentum Builds as Musk Touts Chip Breakthrough
CEO Elon Musk recently revealed that Tesla had completed the design of a new generation of its AI chips for FSD. The company’s “AI5” chip finished the “tape-out” phase, meaning it is now ready for manufacturing. The chip is expected to enter high-volume output in 2027. Musk added that AI6, Dojo3 and other chips are already under development.
Also Read :Schwab launches direct crypto trading in coming weeks to 39 million customers
One of the other reasons for optimism ahead of earnings is the continued momentum in Tesla Energy. Megapack deployments have been scaling rapidly, with the business now contributing meaningfully to both revenue and profitability. Management has repeatedly highlighted energy storage as one of the fastest-growing parts of the company, and analysts expect this segment to deliver strong double-digit growth through 2026 and beyond.
This diversification is important: while automotive margins have faced pressure from pricing adjustments and mix shifts, energy storage offers higher incremental profitability and more predictable demand tied to global renewable energy adoption.
Also Read :Elon Musk says ‘more’ Tesla diners are coming after hinting where the next location could be
Equally compelling is the progress on autonomous driving technologies. Tesla’s shift to a subscription-only model for Full Self-Driving has already begun generating recurring revenue, and the company continues to iterate rapidly on FSD software.
Perhaps the most intriguing long-term driver remains Optimus, Tesla’s humanoid robot project. While still in early stages, management has indicated that limited production could begin later in 2026, with broader commercialization targeted for 2027. The potential scale here is enormous — Tesla has long described Optimus as eventually becoming its largest business by far.
Bottom Line
The upcoming earnings call will likely include updates on regulatory progress, particularly in key markets, as well as early data on Cybercab development. And any tangible updates on development timelines for Optimus could spark renewed enthusiasm.
Also Read :Trump says Iran deal ‘very close,’ may go to Pakistan to sign
Tesla TSLA currently carries a Zacks Rank #3 (Hold), reflecting balanced near-term expectations amid the delivery softness. However, the long-term earnings trajectory remains constructive, with analysts modeling continued EPS growth driven by energy, software, and autonomy.
The combination of resilient underlying fundamentals and a compelling long-term roadmap suggests that Tesla’s recent underperformance may ultimately prove to be a healthy breather before the next leg higher.
Source :Msn